Carro Sets Up S$450 Mn Securitisation Facility, Turning Car Loans into Institutional Capital
The digital marketplace is turning its car loans into a bankable asset, giving its lending arm a funding line that does not depend on new equity as it weighs a public listing.
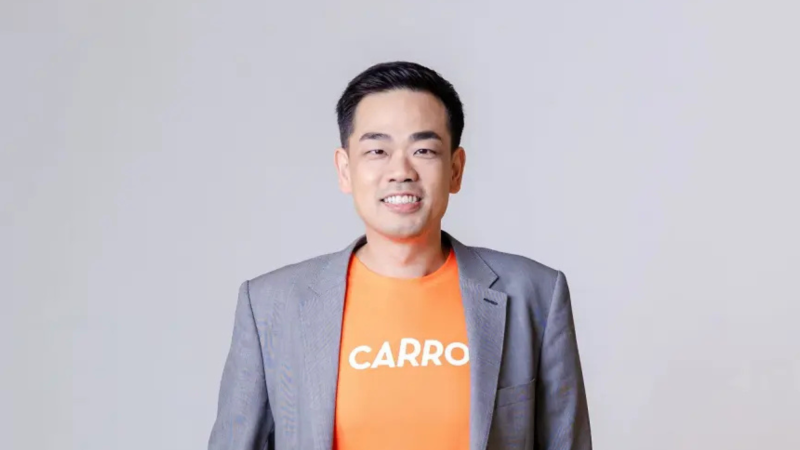
Aaron Tan
Opinions expressed by Entrepreneur contributors are their own.
You're reading Entrepreneur Asia Pacific, an international franchise of Entrepreneur Media.
Carro, a Singapore-based digital auto marketplace, has secured a S$450 Mn (US$352 Mn) asset-backed financing line to fuel the rapid expansion of its auto credit arm across the Asia-Pacific region. The deal is structured as a “warehouse” facility, allowing Carro to fund new auto loans on the ground. Under this arrangement, the company can obtain institutional funding against automotive loan receivables as they are originated, with investors participating through bank loans or capital-markets notes.
The company described the transaction as Singapore’s first-ever asset-backed securitisation (ABS) for automotive loan receivables. Mizuho arranged the deal and, alongside HSBC and JPMorgan Chase, holds the loans and notes.
The facility isolates risk through a bankruptcy-remote special purpose vehicle (SPV) operating under a framework approved by the Monetary Authority of Singapore (MAS). The SPV purchases automotive hire-purchase receivables originated by Carro’s wholly owned lending arm, Genie Financial Services. Carro can draw capital against auto loans Genie originates, while the standalone legal framework shields the underlying loan assets from the parent company’s broader balance-sheet liabilities.
The company said the SPV incorporates independent third-party calculation agents, automated data-integrity controls and fraud-risk safeguards. A planned API integration will provide real-time performance reporting and monitor transaction triggers.
It also leverages Singapore’s certificate of entitlement (COE) to reduce risk in the asset pool. Under this system, a vehicle carries a COE that permits its use for a certain period, usually 10 years. If a vehicle is deregistered before its COE expires, its owner may qualify for a rebate based on the unused validity period. This unexpired entitlement also gives the car a measurable value, even when the borrower stops paying.
Carro said these government-regulated certificates give the vehicles securing the loans a floor value, or underlying collateral value, strengthening the security available to lenders. However, the COE system does not eliminate credit risk or constitute a government guarantee. The rebate declines as the entitlement nears expiry, while recovery values also depend on the vehicle, the borrower’s repayment performance and the applicable financing and enforcement arrangements.
To expand its reach across funding partners, the platform engineered a hybrid format that lets institutions participate on an equal footing via capital markets notes or direct bank loans. Both forms of financing rank equally, or pari passu, within the same SPV.
The hybrid arrangement broadens the range of instruments available to funding institutions. In principle, the structure can release capital tied up in receivables for further lending without requiring the company to wait for borrowers to repay their loans over time.
“By turning automotive loan receivables into an institutional-grade asset class, we are setting a new standard for automotive financing in Southeast Asia,” said Carro’s co-founder and CEO Aaron Tan. As the company prepares for its next growth phase, including a potential dual NASDAQ-SGX listing, the facility gives its lending arm a funding source that does not depend on new equity.
The company has not revealed the loan-to-value ratios, delinquency profile, credit enhancements or recovery assumptions underlying the new facility. But these factors will determine the securitisation’s resilience under weaker credit conditions.
Carro’s Financial Performance & Lending Growth
| Metric | FY24 | FY25 |
| Gross Profit | S$124 Mn | S$149 Mn |
| Gross Profit Margin | 11.8% | 12.4% |
| EBITDA | S$43 Mn | S$43 Mn |
| Genie’s Overall Loan Book | S$496 Mn | Not separately disclosed |
| Genie’s Regional Consumer Loan Book | Not separately disclosed | S$670 Mn |
| Genie’s Non-Performing Loans | Below 0.5% | Below 0.5% |
Sources: Carro’s FY24 financial announcement (December 10, 2024) and FY25 audited-results announcement (October 30, 2025)
Note: Financial years end on March 31. Both loan-book figures cover more than the Singapore loans behind the new facility. The FY24 margin of 11.8% is taken from Carro’s FY25 announcement; its original FY24 announcement rounded the figure to 12%.
Carro reported that Genie’s regional consumer loan book grew 35% to S$670 Mn in FY25, while its FY24 disclosure had put Genie’s overall loan book at S$496 Mn. Non-performing loans remained below 0.5% in both financial years.
The S$450 Mn facility provides an additional funding channel for that business, although it represents a borrowing limit, not an amount already drawn down. Carro has not disclosed how much of the facility has been utilised, the borrowing costs, its maturity or the financial characteristics of the specific Singapore loans backing the transaction.
The distinction matters for a business that combines vehicle retailing with financing, insurance and after-sales services. Unlike a marketplace that primarily earns transaction fees, an automotive lender needs capital to originate loans and sustain a growing portfolio of receivables. As lending grows, the ability to fund those assets becomes a critical determinant of how quickly the business can expand.
A Financing Strategy Built over Years
The latest arrangement marks a significant evolution in Carro’s multi-year campaign to diversify the capital base underpinning its credit business. In June 2024, the automotive marketplace secured a S$75 Mn multi-currency financing facility from HSBC under the bank’s US$1 Bn ASEAN Growth Fund.
Carro secured the five-year facility against a revolving pool of automotive loans to support consumer lending across Singapore and Malaysia. While it signalled the company’s early pivot to asset-backed financing, the structure stopped short of using the hybrid bank-loan and capital-markets-note securitisation model launched in October.
By contrast, the S$450 Mn arrangement is substantially larger in capacity and expands the funding framework to include three global banking heavyweights. It also establishes a Singapore securitisation model that corporate leadership believes can serve as an operational blueprint for future global expansion.
Carro’s chief financial officer, Ernest Chew, said the company is pursuing a mix of longer-term funding channels—including conventional bank loans, block discounting and securitisations—to fuel its next growth cycle. Under standard block discounting arrangements, an external financier purchases a batch of hire-purchase loan receivables at a discount.
The profitability of these models depends on the difference between Carro’s institutional borrowing costs and the interest income generated from its customer loan portfolio, after considering default rates, financial recoveries and core operating expenses. While a larger warehouse line can increase gross lending capacity, it does not automatically ensure lower capital costs or higher net profit margins.
The Business behind Carro’s Growth
Services beyond vehicle sales now generate the majority of Carro’s gross profit. According to its audited FY25 results, released in October 2025, group revenue rose 15% to S$1.2 Bn, while gross profit increased 20% to S$149 Mn. Gross profit margin improved to 12.4% from 11.8%, with ancillary businesses accounting for more than 55% of total gross profit.
However, the group’s EBITDA flatlined at S$43 Mn in FY25, remaining unchanged from the previous fiscal year despite a S$25 Mn increase in gross profit. According to Carro’s regulatory filings cited by DealStreetAsia, rising overheads erased the gains as employee benefit expenses jumped 23.6% to S$99.3 Mn and other operating expenses climbed 23.2% to S$55.3 Mn. Together, these costs rose by about S$29.4 Mn, outrunning the gross profit growth. On its balance sheet, the automotive marketplace closed out FY25 with S$385 Mn in total liquidity and a total asset base of S$1.3 Bn.
The company later said that its EBITDA rose over 50% YoY in the first half of FY26, although it has not yet released audited full-year FY26 results. Although these figures would offer a clearer view of group earnings, assessing the credit arm’s true contribution still requires more detailed financial segment disclosures.
The platform has also attracted a key strategic investor from the consumer finance sector. In September 2026, Japanese consumer-finance group Orient Corporation (Orico) made an undisclosed equity investment in Carro, with the two firms planning to collaborate initially on automotive financing and ancillary businesses in Japan, Thailand and Indonesia. However, replicating the newly established securitisation model outside Singapore will require engineering specific capital frameworks tailored to each target market’s distinct collateral characteristics, financing regulations and local credit conditions.
Ultimately, the more consequential test for Carro will be whether it can use this additional funding capacity to expand its automotive loan portfolio while preserving credit quality and improving overall returns. While Mizuho, HSBC and JPMorgan Chase’s participation significantly broadens the company’s institutional funding base, the volume of capital deployed, its true net cost and the credit performance of the underlying auto loans will determine the facility’s financial contribution.
Carro, a Singapore-based digital auto marketplace, has secured a S$450 Mn (US$352 Mn) asset-backed financing line to fuel the rapid expansion of its auto credit arm across the Asia-Pacific region. The deal is structured as a “warehouse” facility, allowing Carro to fund new auto loans on the ground. Under this arrangement, the company can obtain institutional funding against automotive loan receivables as they are originated, with investors participating through bank loans or capital-markets notes.
The company described the transaction as Singapore’s first-ever asset-backed securitisation (ABS) for automotive loan receivables. Mizuho arranged the deal and, alongside HSBC and JPMorgan Chase, holds the loans and notes.
The facility isolates risk through a bankruptcy-remote special purpose vehicle (SPV) operating under a framework approved by the Monetary Authority of Singapore (MAS). The SPV purchases automotive hire-purchase receivables originated by Carro’s wholly owned lending arm, Genie Financial Services. Carro can draw capital against auto loans Genie originates, while the standalone legal framework shields the underlying loan assets from the parent company’s broader balance-sheet liabilities.