The Buyout Battle: Warburg Asks Ingenia to Judge Its A$2.14 Bn Bid Against the Peet Deal
With the price capped, Warburg wants Ingenia’s board to weigh a potential cash exit against the Peet acquisition whose land-lease conversion earnings are not expected until FY29 or FY30.
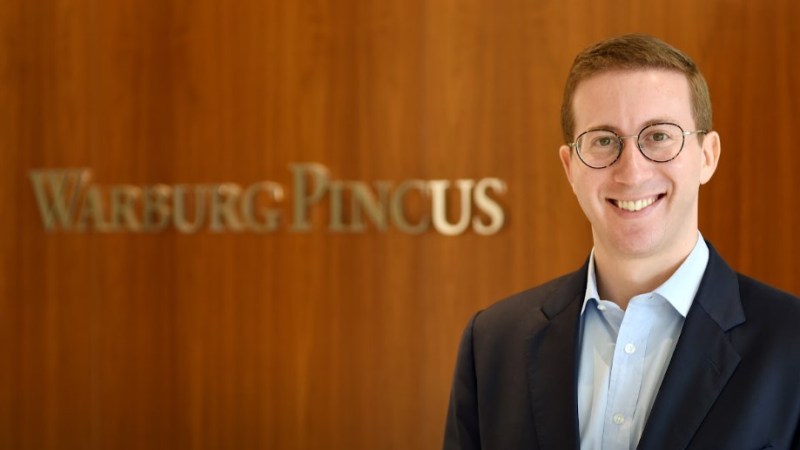
Jeffrey Perlman, Chief Executive Officer of Warburg Pincus
Opinions expressed by Entrepreneur contributors are their own.
You're reading Entrepreneur Asia Pacific, an international franchise of Entrepreneur Media.
Warburg Pincus has given Ingenia Communities until Monday (October 19) to decide whether its A$2.14 Bn takeover offers more value than the Australian land-lease and holiday park operator’s planned acquisition of Peet. The US buyout firm is also seeking exclusive access to the remaining due diligence materials.
The New York-based buyout firm has reaffirmed its A$5.25-per-security cash proposal for Ingenia after reviewing initial due diligence materials, declaring the price “best and final” unless a superior proposal emerges. But the latest terms suggest the contest now involves more than price. Warburg wants Ingenia’s board to establish whether selling the business would be more favourable to investors than proceeding with the A$992.5 Mn acquisition of Perth-based residential property developer Peet.
What Warburg is Seeking
The October 19 deadline does not require Ingenia to accept the takeover bid. Instead, Warburg is seeking a conditional judgement that its proposal would deliver greater value, assuming the firm completes its outstanding due diligence, reconfirms the pricing and negotiates binding agreements, provided no superior proposal emerges. It also wants exclusive access to the remaining due diligence materials, subject to an agreed process deed.
That marks a shift in what Warburg is asking for. Its September 25 terms required Ingenia’s directors to confirm their intention to recommend the offer. The new condition sets a lower bar, but it still asks the board to rank the two competing transactions before exclusive due diligence begins.
Nevertheless, the revised proposal will permit Ingenia securityholders to maintain a distribution of up to A$0.05 per stapled security for the half-year ending this December, without affecting the A$5.25 cash consideration.
Warburg’s earlier proposals would have deducted any such payout from the price. The concession, worth up to about 1% of the offer, improves investor economics without raising the headline offer price.
Ingenia’s board, however, has not yet determined whether the proposal or its conditions are acceptable and has made no recommendation to securityholders.
The standoff follows two rejected approaches from Warburg: initially at A$4.75 per security in August and later at A$5.05 in September. Ingenia considered both proposals to be substantially below the company’s value. A third approach at A$5.25 led the board to grant initial, non-exclusive due diligence access earlier this month.
The Case for Peet
The disagreement centres on the value of Ingenia’s expansion strategy. The Sydney-based company, a member of the S&P/ASX 200, operates land-lease communities, rental accommodation and holiday parks, with a substantial focus on Australia’s ageing population. The group has 96 communities and development sites.
Ingenia’s proposed acquisition of Peet, announced in August, would combine that operating platform with one of the country’s established residential land development businesses, founded in 1895.
Peet shareholders would receive A$0.68 in cash and 0.3367 Ingenia stapled securities for each share, implying A$2.12 per share based on Ingenia’s 10-day volume-weighted average price of A$4.28 up to August 21, before the transaction was announced. Including Peet’s A$0.065 final dividend, paid in September, the transaction’s original implied total value was A$2.185 per share.
For Ingenia, the appeal is securing a development pipeline in one transaction. The company argues that competition for land-lease sites is rising as new operators enter the market, making it difficult to assemble such a pipeline through individual land acquisitions.
Peet brings approximately 26,400 residential development lots across 37 projects, compared with Ingenia’s existing pipeline of around 8,800 land-lease development sites. Ingenia estimates it could convert 5,000-7,000 lots across Peet’s portfolio into land-lease communities, creating an indicative end value of about A$1 Bn.
But those conversions will take time. About 15% of the identified lots still need rezoning. Less than half sit in projects Peet wholly owns, with the rest in syndicates, joint ventures or development management agreements.
Ingenia does not expect the conversions to add earnings until FY29 or FY30. Nevertheless, they underpin the company’s argument that the acquisition would provide a longer development runway and recurring rental income.
The company has also projected 11% pro forma FY26 earnings-per-security accretion from the combination, based on transaction assumptions that include the proposed Flagstone joint venture. The calculation assumes the deal had taken effect on July 1, 2025, and includes A$10 Mn in annual cost savings, so it is an estimate, not a realised gain.
Flagstone is central to the transaction’s financial structure. Ingenia has agreed to a term sheet under which private developer Brown-Neaves Investments would acquire a 49.9% interest in Peet’s flagship Queensland development, Flagstone City, at an enterprise valuation of A$615 Mn for the whole project.
The arrangement is expected to release capital and support the enlarged group’s balance sheet, but remains subject to confirmatory due diligence and definitive agreements. Establishing the joint venture is also a condition of the Peet acquisition.
Strategic Play
Ingenia would not be Warburg’s first bet on ageing populations. The firm began investing in Asian real estate in 2005, and its living-sector platforms across Asia-Pacific include Weave Living, China’s Vlinker and a senior housing venture formed in March 2025 with South Korea’s SK D&D. That venture targets Greater Seoul’s ageing population, the same demographic trend that underpins Ingenia’s business.
Warburg has not publicly stated why it wants the Peet deal dropped, beyond presenting its cash offer as a superior alternative for Ingenia investors. Ingenia’s own pro forma figures show what the acquisition would change.
The group would issue about 160 Mn new securities to Peet shareholders, lifting the number on issue from 408 million to about 567 million. Net debt would rise from A$0.9 Bn to A$1.2 Bn, and the residential lot pipeline would grow from about 8,800 to more than 35,000. Any buyer would take on a larger group, far more exposed to land development.
Warburg’s proposal, therefore, challenges a strategy built around securing residential land, converting part of that portfolio into recurring-income assets and using third-party capital to finance further development.
It offers Ingenia investors a cash exit instead of requiring them to wait for those gains to materialise. But that certainty isn’t available today. The proposal remains non-binding and subject to further diligence, financing commitments, investment committee approval and definitive documentation.
The market has reflected that uncertainty. Ingenia securities fell 11.57% to A$4.05 on Thursday (October 15), substantially below Warburg’s A$5.25 proposal. Peet shares gained 2.19% to A$1.63. Ingenia’s discount to Warburg’s price widened to about 23%, up from 13% the day before. The fall also cut the value of the Peet scheme consideration to about A$2.04 a share, leaving Peet trading at an approximately 20% discount and underscoring market uncertainty over the competing transactions.
The Clock on Peet’s Scheme
The competing transaction also carries contractual consequences. Ingenia’s agreement with Peet permits termination for a superior proposal under specified conditions, including the board’s assessment of its directors’ duties. Exercising that right would make Ingenia liable for a reverse break fee of A$10 Mn, less than 0.5% of the A$2.14 Bn equity value Warburg has put on Ingenia.
Meanwhile, Peet has continued advancing its proposed combination with Ingenia. On October 12, the company confirmed that it had lodged its draft scheme booklet, including a draft independent expert’s report, with Australia’s corporate regulator on October 9.
Its board recommends the transaction, subject to the independent expert’s assessment and the absence of a superior proposal. Shareholders are likely to vote in early December, and the deal may be completed later that month.
Ingenia’s room to manoeuvre narrows as that timetable advances. Peet’s first court hearing is targeted for late October, and the scheme booklet is due to reach its shareholders in early November. Ingenia can terminate the Peet agreement for a superior proposal only until the second court hearing, scheduled for early December.
The pressure is now on Ingenia’s directors. Warburg has said it will not offer a higher price unless a competing proposal turns up. Meanwhile, Ingenia has to weigh the benefits of a cash exit against the expected earnings and development opportunities that come with a larger property platform.
Monday’s deadline will not settle who owns Ingenia. It will determine whether the board is prepared to give Warburg a clearer path towards a binding offer, potentially at the expense of an acquisition already moving towards a shareholder vote.
Also Read:
Warburg Pincus Raises Ingenia Bid to $1.47 Bn, but Peet is Still a Sticking Point
KKR Exits Power Producer First Gen in $411 Mn Sale After Expansion Bid Fails
Warburg Pincus has given Ingenia Communities until Monday (October 19) to decide whether its A$2.14 Bn takeover offers more value than the Australian land-lease and holiday park operator’s planned acquisition of Peet. The US buyout firm is also seeking exclusive access to the remaining due diligence materials.
The New York-based buyout firm has reaffirmed its A$5.25-per-security cash proposal for Ingenia after reviewing initial due diligence materials, declaring the price “best and final” unless a superior proposal emerges. But the latest terms suggest the contest now involves more than price. Warburg wants Ingenia’s board to establish whether selling the business would be more favourable to investors than proceeding with the A$992.5 Mn acquisition of Perth-based residential property developer Peet.
What Warburg is Seeking